

For many people, the idea of owning a first home in Kuala Lumpur can feel exciting and intimidating at the same time. Rent is due every month, everyday expenses continue to rise, and saving for a deposit may take longer than expected. At the same time, property advertisements can make buying appear simpler than it really is. A headline about a low monthly instalment or a furnished unit may catch your attention, but a sound decision requires more than an attractive offer.
The good news is that exploring your first home does not mean you must commit immediately. It means giving yourself the opportunity to understand the choices, ask better questions and work out whether ownership fits your finances and plans. This guide takes a practical, problem-solution approach: it looks at the pressures renters may face, explains what to check before buying, and outlines how to assess the advertised home options in Kuala Lumpur.
The moment the question changes: “Could I own a home?”
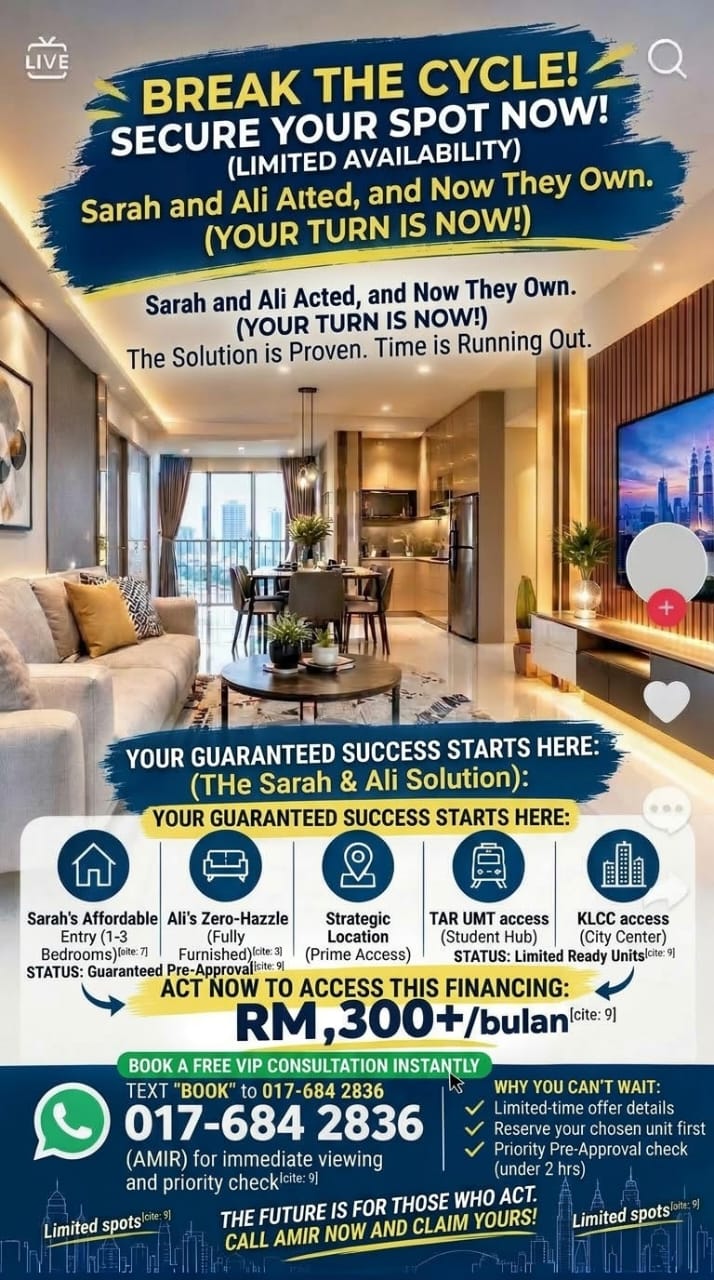
Imagine Sarah, a young professional who has rented for several years. She values the flexibility of renting because it allows her to live close to work without taking on a long-term financing commitment. Yet each time the tenancy renewal approaches, she wonders whether she should continue renting or begin exploring home ownership. Her concern is familiar: she pays rent regularly, but she is not building ownership in the property where she lives.
Her friend Ali suggests that she should not compare rent with a mortgage instalment alone. Buying also involves a deposit, legal and valuation costs where applicable, stamp duty, maintenance charges, insurance or takaful, utilities, repairs and other expenses. Sarah realises that the question is not simply, “Is the monthly instalment lower than my rent?” It is, “Can I afford the full cost of owning this home while maintaining a healthy financial life?”
Sarah’s story is fictional and is used only to illustrate a common decision. It highlights an important point: buying a home is not automatically better than renting for everyone. The right choice depends on income stability, savings, existing commitments, financing eligibility, household needs, location and how long a person expects to stay. Renting can remain sensible when someone needs flexibility or has not yet built a financial buffer. Buying may become worth exploring when the numbers, property and long-term plans align.
Why the first-home decision can feel difficult
For first-time buyers, the challenge is often a combination of financial pressure and uncertainty. A person may have a regular salary but still feel that a deposit is out of reach. Another may have savings but be unsure how banks assess applications. Some buyers understand the monthly payment but have not considered maintenance fees, furnishing costs or the possibility of repairs. Others are attracted to a location but have not tested the daily journey to work, campus or family responsibilities.
Online property information can add to the confusion. Advertisements are designed to attract attention, so they often highlight the most appealing features first. That is not necessarily a problem; marketing can help buyers discover opportunities. However, a buyer should treat promotional statements as the beginning of a conversation, not as a substitute for documents, a viewing and independent checks. Ask for the exact address, the full purchase price, the layout, the furnishing inventory, the applicable charges and the status of the property.
There is also an emotional dimension. A first home can represent independence, security and a new stage of life. Those feelings are understandable, but they can encourage rushed decisions. A useful way to protect yourself is to separate the dream from the decision process. Keep the dream as motivation, then use a checklist, realistic calculations and a proper viewing to decide whether a particular property deserves serious consideration.
What should first-time home buyers look for?
A practical search begins with the needs of the people who will live in the home. A single buyer may prioritise manageable costs, access to public transport and a convenient work commute. A couple may need space for working from home or plans for a growing household. A small family may place greater importance on bedrooms, storage, nearby schools, healthcare and safe access to everyday facilities. There is no universal best layout; the right choice is the one that supports the household without stretching its finances.
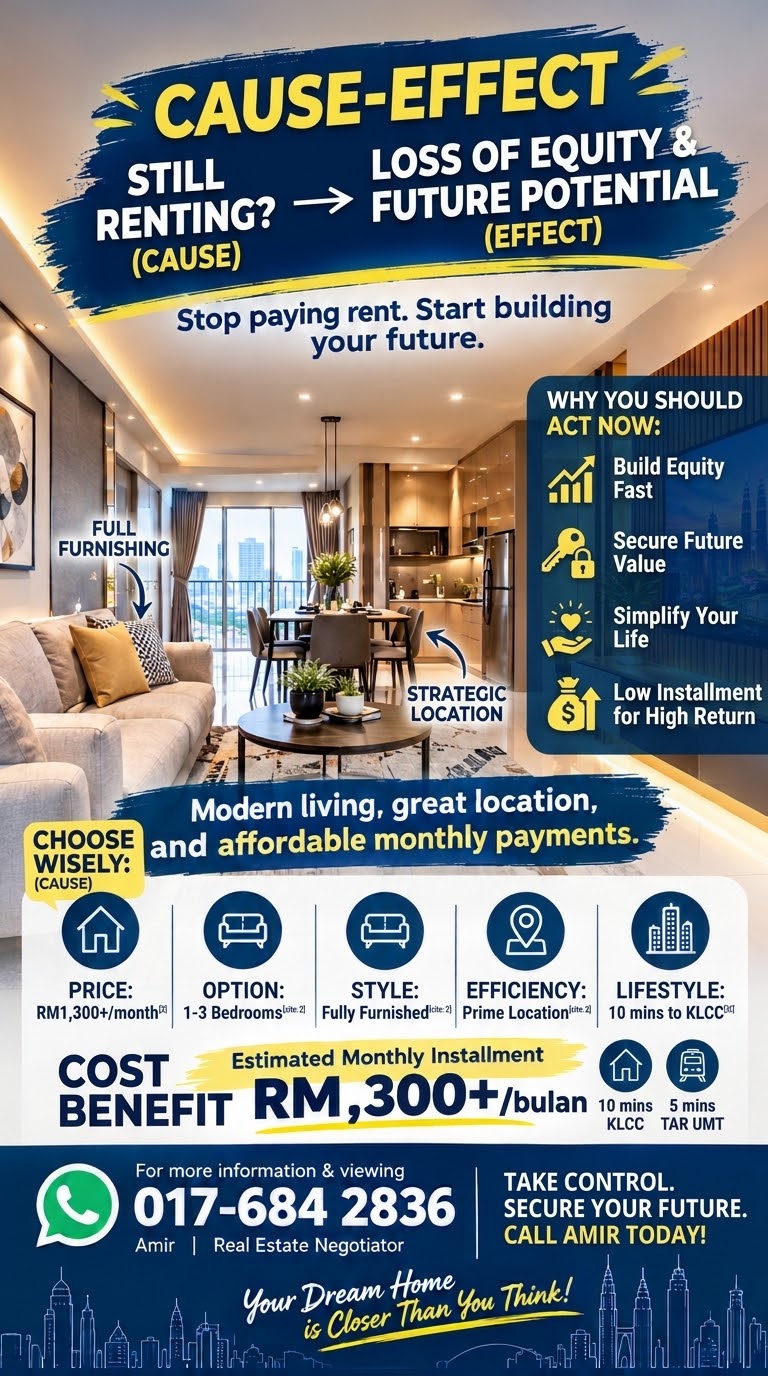
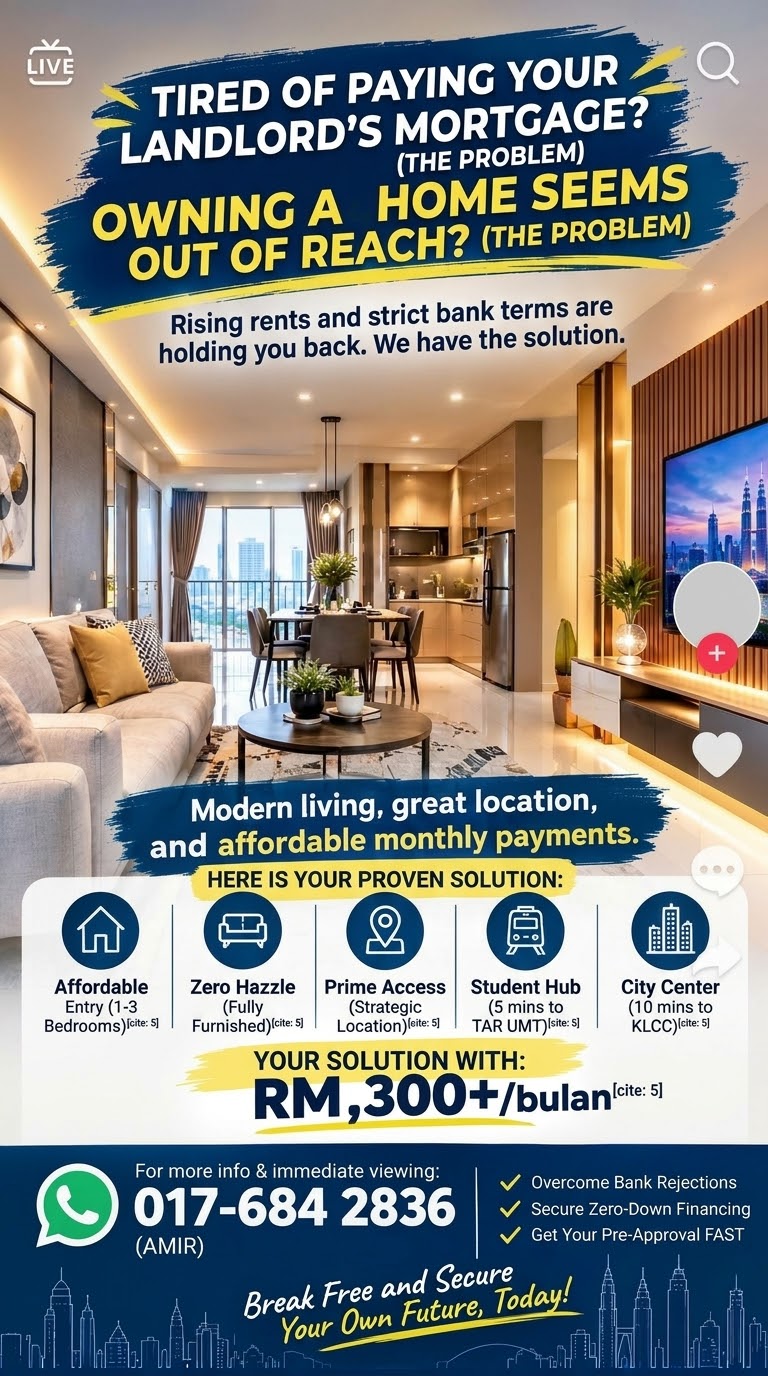
For this advertised opportunity, the options described include 1-bedroom, 2-bedroom and 3-bedroom layouts, with fully furnished units. These configurations may appeal to different household sizes and living arrangements. However, buyers should confirm the actual floor area, room dimensions, floor plan, furniture list and whether the furniture shown in photographs is included. The phrase “fully furnished” should be supported by a written inventory so there is no misunderstanding about appliances, beds, wardrobes, curtains, lighting or other items.
The promotional information also describes access to TAR UMT in approximately five minutes and KLCC in approximately ten minutes. Treat these as indicative travel estimates only. Actual journey times depend on the exact property address, route, mode of transport, time of day and traffic conditions. Before making a decision, check the route yourself, test the journey at the time you would normally travel and identify alternatives during peak periods or severe weather.
Location: look beyond the distance on an advertisement
Location affects more than convenience. It influences transport costs, time spent commuting, access to work and education, the availability of groceries and services, and the way a household uses its free time. A home that appears close to a destination on a map may still involve a difficult journey because of road conditions, traffic patterns, parking or the need to change transport modes. Conversely, a slightly longer route may be more predictable or affordable.
When evaluating a Kuala Lumpur property, identify the destinations that matter most to your household. These may include your workplace, TAR UMT, KLCC, public transport stations, supermarkets, clinics, hospitals, childcare facilities, schools, places of worship and family support networks. Do not assume that every nearby facility is easy to reach on foot. Check pedestrian routes, crossings, lighting, accessibility and whether the journey is practical in hot weather or heavy rain.
Visit the neighbourhood at more than one time if possible. A daytime visit can show how the area functions during ordinary hours, while an evening visit may reveal parking pressure, noise, lighting and the general atmosphere after work. If you are considering a unit near a busy road, ask about traffic noise and inspect the windows. If you rely on a car, check the parking allocation and visitor parking arrangements. If you rely on public transport, walk the route to the nearest stop or station rather than relying only on a distance figure.
It is also worth considering future changes. New transport links, commercial developments or road projects may affect an area, but proposed projects should not be treated as guaranteed benefits. Verify the status and timing of any development through reliable official information. Make your decision based on what is available and practical today, while treating possible future improvements as uncertain rather than promised.
Understanding 1-, 2- and 3-bedroom choices
A 1-bedroom unit may suit a single occupant or a couple who prefer a compact home and have limited furniture requirements. Its smaller footprint may make cleaning and furnishing more manageable. Before choosing it, consider storage, privacy, work-from-home needs and whether there is enough room for visitors. A layout that looks attractive in a photograph may feel different when you place your everyday belongings inside it.
A 2-bedroom unit can offer greater flexibility. One room may be used as a bedroom and the other as a study, guest room or space for a child. That flexibility is valuable, but it should be balanced against the higher purchase price or monthly charges that may apply to a larger unit. Buyers should ask whether the second room can accommodate the furniture and activities they have in mind, and whether the layout provides sufficient privacy.
A 3-bedroom unit may be more suitable for a household that needs separate rooms for children, relatives or work. It can also provide flexibility as circumstances change. However, a larger unit usually brings additional space to maintain and furnish. Do not choose more bedrooms simply because they seem like better value. Consider the total cost, how each room will be used and whether the household can comfortably maintain the property over time.
Ask for the floor plan of the exact unit being offered. Compare usable space, room proportions, window positions, kitchen arrangement, bathroom access, ventilation and storage. During a viewing, imagine normal routines: preparing meals, getting ready for work, studying, resting and accommodating guests. A thoughtful layout can make a modest home feel practical, while a poorly arranged larger unit may not meet your needs.
What does fully furnished really mean?
A furnished home can reduce the immediate effort of setting up a new place. It may be especially helpful for buyers who are moving from a rented room, relocating for work or studying, or trying to avoid a large one-off furniture purchase. Yet the term “fully furnished” can mean different things in different listings. One property may include major appliances and bedroom furniture, while another may provide only selected items.
Request a written inventory before paying a booking fee or signing an agreement. Ask whether the list includes the refrigerator, washing machine, cooker, air-conditioning units, water heater, beds, mattresses, wardrobes, sofa, dining table, curtains and lighting. Confirm the quantity, condition and ownership of each item. If an item is shown in marketing photographs but is not included, ask for that distinction to be made clear in writing.
During a viewing, inspect the furniture and appliances rather than assuming that everything is new or covered by a warranty. Check doors, hinges, drawers, upholstery, electrical sockets and visible signs of wear. For appliances, ask whether manuals, warranties or service records are available. If a defect is identified, record it and clarify whether it will be repaired before handover. Photographs taken during the inspection can help both parties keep an accurate record.
Furnishing should be treated as a convenience, not as a reason to overlook the fundamentals. A beautifully styled living room cannot compensate for an unsuitable location, unclear legal status, poor maintenance or unaffordable financing. First assess the property itself; then decide whether the furnishing package adds genuine value to your household.
Can the monthly instalment start from RM1,300+?
The promotional information for this opportunity indicates an estimated monthly instalment from RM1,300+. This figure may help a prospective buyer begin a conversation, but it must be treated as an illustration rather than a guaranteed payment, a confirmed offer or a promise of financing approval. The actual instalment depends on the property’s confirmed purchase price, deposit, financing amount, loan tenure, interest or profit rate, fees and the lender’s assessment of the applicant.
Two people considering the same property may receive different financing outcomes. Their income, employment history, existing debts, credit records, age, deposit and other financial circumstances may differ. A bank or other financing institution will apply its own assessment criteria. A property representative can help explain the information supplied for the property, but cannot guarantee that a bank will approve an application or offer a particular rate.
Ask for a written financing illustration based on the confirmed price and the amount you may need to borrow. Check the assumptions behind the illustration: how much deposit is included, what tenure is used, what rate is assumed and whether any fees are excluded. If the figure is described as “from”, ask what conditions would make a buyer eligible for that estimate. A low starting figure may not reflect the amount that applies to every unit or every buyer.
Do not build your budget around the most optimistic estimate. Consider whether you could still manage the payment if rates changed, household income fell or an unexpected expense arose. If you are unsure, speak directly with a qualified financing officer and compare more than one suitable option. The aim is not simply to obtain the largest financing amount available. It is to choose a commitment that remains manageable in real life.
Build a realistic first-home budget
A responsible budget includes more than the monthly instalment. Start by listing your regular net income and essential monthly expenses. Include food, transport, utilities, phone and internet bills, insurance or takaful, family support, education costs, existing loans and credit-card payments. Add a realistic allowance for savings and emergencies. What remains is a more useful starting point for assessing housing costs than your gross salary alone.
Next, identify the one-off costs associated with buying. Depending on the transaction and applicable rules, these may include the booking or earnest deposit, balance deposit, stamp duty, legal fees, loan documentation costs, valuation fees, insurance or takaful and moving expenses. Some costs may be subject to exemptions, promotions or specific arrangements, so ask for an itemised breakdown and verify which party is responsible for each payment. Do not assume that an advertised package covers every expense.
Then estimate the recurring costs of ownership. These may include maintenance charges, sinking fund contributions, utilities, internet, assessment rates, quit rent where applicable, insurance or takaful, parking charges and routine repairs. The exact items depend on the property type and ownership arrangements. Ask the representative or management office for the current charges and relevant documents. If the property is strata-titled or managed as a shared development, understand what the maintenance payments cover and how building management is organised.
Finally, keep an emergency reserve. A buyer who uses every available ringgit for the deposit and moving costs may be vulnerable when an appliance fails, medical expense arises or income is interrupted. The right reserve varies according to household circumstances, but the principle is straightforward: home ownership should not leave you without a financial safety net. If the numbers only work when every month goes perfectly, pause and reassess.
A simple affordability check before you enquire
Before contacting a property representative, prepare a private summary of your finances. You do not need to share sensitive account details in an initial enquiry. Instead, understand your approximate monthly income, existing commitments, available savings and the amount you could reasonably allocate to housing. This preparation helps you ask focused questions and avoid being persuaded by a figure that does not match your circumstances.
- Income: Work out your reliable take-home income, allowing for variable commissions, overtime or business earnings to fluctuate.
- Commitments: List car financing, personal loans, education loans, credit-card balances and other regular obligations.
- Savings: Separate money available for the purchase from your emergency reserve and other important goals.
- Upfront costs: Request a written estimate of deposits, legal costs, duties, valuation and moving expenses.
- Monthly ownership costs: Include the estimated instalment, maintenance, utilities, insurance and a repair allowance.
- Future changes: Consider possible changes in employment, family size, transport needs or other commitments.
This is an initial self-check, not a substitute for a bank’s assessment or professional financial advice. If the result looks tight, consider reducing other debts, building savings or looking at a different price range. A sensible decision may be to wait. Waiting with a plan is better than rushing into a commitment that creates long-term stress.
Documents and questions to request before paying
Good property decisions are supported by clear information. Ask for the full property address, the name and details of the seller or authorised party, the unit type, floor plan, built-up area, asking price and the current availability status. Confirm whether the unit is new, completed, under construction or a subsale property, as the checks and transaction process may differ. Ask which documents can be provided for your review and who will explain the transaction terms.
Clarify what is included in the price. Ask whether parking bays are included, whether furniture and appliances are part of the sale, whether any renovation or repair work is outstanding and whether there are additional charges. If the property is part of a managed development, request information about maintenance charges, sinking fund contributions, facilities, house rules and any known management issues that a prospective buyer should investigate.
Before paying money, understand who receives it, why it is being collected, whether it is refundable and what written document records the payment. Never rely only on a verbal assurance or an informal message. Check the identity and authority of the person or agency handling the transaction, verify payment instructions independently and retain receipts and copies of all documents. If anything is unclear, obtain independent legal advice before signing or transferring funds.
Buyers should also understand the relevant title and transaction status. The exact checks depend on the property and circumstances. A conveyancing lawyer can advise on ownership, restrictions, encumbrances, approvals, sale and purchase documentation and other legal matters. Do not assume that a marketing brochure is proof of legal status. A proper review helps you understand what you are buying and what obligations come with it.
Make the viewing count
A viewing is an opportunity to test whether the property matches the description and your everyday needs. Arrive with a list of questions and take notes. Check the entrance, common areas, lift condition, corridors, security arrangements, parking, refuse areas and visible maintenance. Inside the unit, inspect walls, ceilings, floors, windows, doors, plumbing, water pressure, electrical points, ventilation and signs of dampness or leakage. Ask permission before taking photographs or videos.
Pay attention to natural light and airflow. A room may look spacious in a wide-angle photograph but feel different in person. Stand where you would normally work, cook or rest. Check whether furniture blocks movement, whether there is enough storage and whether the kitchen and bathrooms are practical. If you work from home, consider internet availability, noise and a suitable place for calls. If you have children or older family members, think about access, safety and the distance between rooms.
Do not hesitate to ask about defects. If you notice a stain on the ceiling, a damaged fitting or a door that does not close properly, ask what caused it and whether it will be rectified. A seller or representative may not know the answer immediately; request clarification in writing where the issue could affect your decision. If you are seriously interested, consider arranging a more detailed inspection by an appropriately qualified professional.
After the viewing, take a moment to compare what you saw with the advertisement. List what matched, what differed and what remains unanswered. This simple habit reduces the chance of making a decision based only on first impressions. A home should feel suitable in practical terms, not merely attractive in photographs.
Renting versus buying: compare the whole picture
Renting offers flexibility. It may be suitable for people whose work location could change, who are building savings, or who do not want responsibility for property maintenance and long-term financing. The tenant’s responsibilities depend on the tenancy agreement, but major ownership decisions and some property-related risks generally remain with the owner. Renting can also make it easier to move when household needs change.
Buying can provide a sense of stability and the opportunity to own an asset, but it comes with responsibilities. Owners must plan for financing payments, maintenance, repairs, insurance, taxes and the possibility that the property may not be easy to sell quickly. Property values can rise or fall, and transaction costs can be significant. A buyer should not assume that ownership guarantees a profit or that the property will automatically increase in value.
To compare fairly, calculate the total cost of renting over the period you expect to stay, including rent increases where relevant. Then estimate the total cost of buying over the same period, including upfront costs, monthly payments, recurring charges, maintenance and likely selling costs if you may move. This is not a simple calculation because the future value of a property, interest rates and personal circumstances are uncertain. Nevertheless, comparing like with like can reveal whether buying is financially sensible for your situation.
Also consider the value of flexibility. If you expect to relocate in a year or two, buying may expose you to transaction costs and the risk of having to sell at an inconvenient time. If you expect to stay for a longer period and can afford the commitment, ownership may deserve closer consideration. The best answer is personal; it should emerge from your needs and financial position rather than pressure from an advertisement, friend or relative.
Common first-time buyer mistakes and how to avoid them
Focusing only on the monthly instalment. A low estimate can attract attention, but it does not show the full cost of ownership. Ask for a complete breakdown and include recurring charges, one-off costs and a financial buffer in your budget.
Assuming financing is guaranteed. No advertisement or representative can replace a lender’s assessment. Treat every instalment figure as indicative until a financing institution has assessed your application and issued its terms. Do not make a non-refundable commitment based on an assumption that approval will follow.
Not checking the exact location. Approximate travel times can change with traffic, routes and transport choices. Confirm the address, test the journey and visit the neighbourhood at different times. Check noise, parking, access and the facilities you actually use.
Taking “fully furnished” at face value. Ask for an inventory and inspect the actual items. Confirm what remains with the property at handover and record the condition of furniture and appliances.
Using all savings for the purchase. A deposit is important, but so is an emergency reserve. Budget for moving, repairs and unexpected expenses. If buying would leave you financially exposed, pause and rebuild your savings first.
Skipping the legal and document checks. Review the transaction documents carefully and use an independent conveyancing lawyer where appropriate. Verify payment instructions, keep receipts and make sure you understand refund terms and contractual obligations before signing.
Deciding after one quick viewing. Take notes, inspect the unit and common areas, ask follow-up questions and revisit if necessary. A home is a major commitment; it deserves more than a rushed decision.
A practical step-by-step path from enquiry to decision
Step 1: Define your needs. Decide who will live in the home, how many bedrooms you need, where you travel regularly and what facilities matter. Separate essential requirements from preferences. This makes it easier to compare properties objectively.
Step 2: Set a comfortable budget. Review income, debts, savings and monthly expenses. Include the full cost of ownership and preserve an emergency reserve. Do not rely on the maximum financing amount a lender might offer as proof that the payment is comfortable.
Step 3: Request verified property information. Ask for the exact address, current price, unit availability, floor plan, built-up area, furnishing list, parking details and applicable maintenance charges. Request clarification of every promotional claim that could affect your decision.
Step 4: Explore financing independently. Speak with a bank or qualified financing professional about eligibility, deposit requirements, tenure, rates and fees. Compare the written terms and understand that approval is subject to the lender’s assessment.
Step 5: Arrange a viewing. Inspect the unit, building and neighbourhood. Check the route to work or study, ask about defects and compare the actual property with the information you received.
Step 6: Review documents and obligations. Understand the payment process, refund terms, sale and purchase agreement, title status and any restrictions or charges. Obtain independent legal advice where needed before signing.
Step 7: Decide without pressure. If the facts, finances and property meet your requirements, you can consider the next step. If important information is missing or the numbers do not work, ask for clarification or walk away. A genuine opportunity should withstand careful questions.
Questions to ask the property representative
- What is the exact property address and which route supports the stated travel estimates?
- What are the current prices for the 1-bedroom, 2-bedroom and 3-bedroom options?
- Which units are currently available, and can availability be confirmed in writing?
- What is the built-up area and can I receive the floor plan for the exact unit?
- What furniture and appliances are included, and can I receive a written inventory?
- Is the quoted RM1,300+ monthly instalment an illustration? What price, deposit, tenure and rate assumptions are used?
- What are the maintenance charges, sinking fund contributions and other recurring costs?
- What payments are required before signing, who receives them and what are the refund conditions?
- What is the property’s completion, title and transaction status?
- Can I arrange a viewing and review the relevant documents before making a decision?
These questions are not intended to make the process difficult. They help both the buyer and the representative establish whether the property is suitable. Clear answers early in the process can save time, reduce misunderstandings and create a more confident experience.
Explore the available home options in Kuala Lumpur
If you are currently renting and would like to explore the advertised opportunity, you can request details of the 1-bedroom, 2-bedroom and 3-bedroom options. The promotional information describes fully furnished units and approximate access to TAR UMT and KLCC. Before deciding, ask for the exact address, current availability, full price, floor plan, furnishing inventory, recurring charges and a personalised financing illustration based on your circumstances.
You can also arrange a discussion or viewing to assess whether the property suits your daily routine. An enquiry does not oblige you to buy. Use the conversation to obtain information, compare the options and decide whether the next step is right for you. If the property or financing does not fit your needs, it is reasonable to continue your search.
For property details or to arrange a discussion:
WhatsApp: +60 17-684 2836
A first home should support your life, not strain it
The move from renting to owning can be an important milestone, but it should be guided by preparation rather than urgency. The strongest first-home decision is not necessarily the biggest unit or the lowest advertised instalment. It is a property that fits your household, location needs and financial capacity, with the documents and costs clearly understood.
Start with the questions that matter: Can I afford the full commitment? Is the location practical? Does the layout suit my household? Are the furnishing details clear? Have I checked the legal and financing requirements? When you have reliable answers, you can move forward with greater confidence—or decide that waiting is the wiser choice for now.
Your first step does not have to be signing an agreement. It can simply be asking for accurate information, reviewing the numbers and arranging a viewing. A careful enquiry today can help you make a better-informed decision about where you may want to live tomorrow.
Important information: This article provides general information and is not financial, legal or tax advice. Property features, availability, prices, travel times and estimated instalments are subject to confirmation by the relevant property representative and parties. The RM1,300+ figure is an indicative promotional estimate only and is not a guaranteed instalment or financing approval. Financing is subject to the lender’s assessment and approval. Buyers should verify all details, review transaction documents and obtain independent professional advice where appropriate. Sarah and Ali are fictional characters used solely for illustration.
